Boat Insurance in Ocala, FL

Boat insurance in Ocala: a homeowners policy is not boat insurance, and a boat on a lift at your dock is not automatically covered.

On InsuranceOcalaFL.com, Matt Williams, a licensed Florida agent, compares 80+ companies for you.

  • $0 to compare; the company pays the agent
  • 21,862 vessels registered in Marion County, 2025 (FLHSMV)
  • Born 1988 or later? Boating ID for 10 hp or more (s. 327.395)
  • Most boats on Florida waters must be registered (s. 328.48)
  • Keep the registration aboard when the boat runs (s. 328.48)

Lakefront home? Check the flood zone

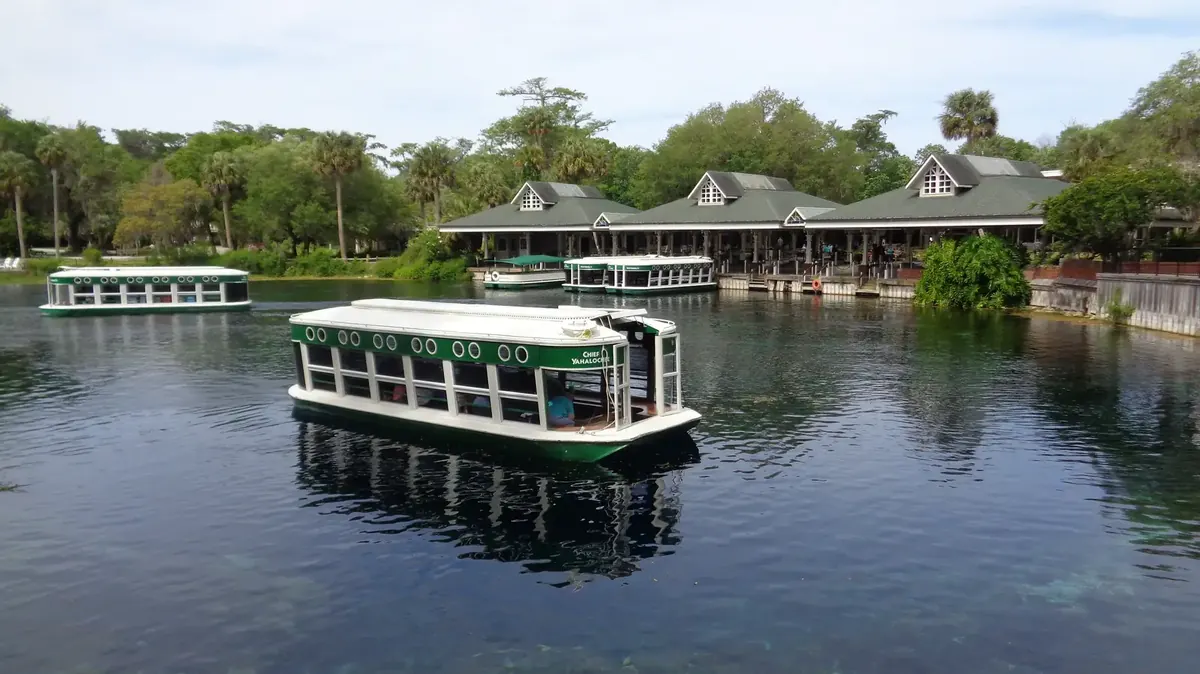
Glass-bottom boats at Silver Springs State Park near Ocala, Florida
Glass-bottom boats, Silver Springs State Park

One call takes about five minutes, and asking changes nothing on your current policy.

Tell us where it goes and where it sits: local lakes and rivers and trailering to the coast are different risks on the same policy form.

Your Homeowners Policy Is Not Boat Insurance

A homeowners policy may include a limited watercraft liability extension and a small sublimit for the hull, generally designed with small, low-powered boats in mind rather than a boat with a real motor on it. Anything with meaningful horsepower or value typically outgrows it quickly.

A common trap is the boat on a lift. A boat stored at a dock is not automatically covered by the policy covering the house, and the dock itself is often sublimited too.

What a Boat Policy Actually Pays For

  • Hull physical damage: on an agreed value or actual cash value basis, and the difference matters at total loss
  • Liability: injury or damage you cause on the water
  • Uninsured boater: the same logic as uninsured motorist coverage on a car, on water
  • Medical payments: for people aboard
  • Wreck removal: the cost of removing a sunken boat, which can be a real obligation
  • Trailering: some losses happen on the road, not the water
  • Personal effects, fishing gear and electronics: usually sublimited by default

Agreed Value or Actual Cash Value

Agreed value fixes the payout at total loss. Actual cash value depreciates it. On an older hull the premium difference is usually the deciding factor, and it should be a decision rather than a default.

Every boat policy defines where the boat is covered. A policy written for inland lakes may not cover a run offshore, and coastal cruising limits are typically defined by distance from shore.

For a Marion County boat that mostly stays on the lakes but occasionally trailers to the coast, the navigation limits and the trailering coverage are the two clauses to read before anything else. Tell the agent the furthest trip you actually make, not the typical one.

Where Marion County Boats Live Changes What You Pay

Local water includes Lake Weir, the Silver River, which runs east from Silver Springs to the Ocklawaha River, and the Rainbow River where it joins the Withlacoochee at Dunnellon. The community of Ocklawaha sits on the north shore of Lake Weir. Lakes and rivers can carry different hazards, such as shallow-water hull damage and submerged obstacles after storms. The same water decides whether a lakefront house needs its own flood policy. Boats trailered to the coast add highway exposure on top, which brings the car pulling the trailer into the same conversation.

Storage matters as much as use. A boat kept on a lift, one on a trailer beside the house and one in a covered rack rate differently, and hurricane haul-out provisions vary by carrier. Storage carries the same weight on an RV parked on a pad at home.

What Moves Boat Insurance Rates in Ocala, and What You Can Change

Length, hull type, horsepower and value carry most of it. After that: the operator's boating and driving record, whether a boating safety course has been completed, where the boat is stored, and the navigation territory you actually use.

Boat Insurance Questions

Who requires boat insurance?

A marina or lender may require it, so check the terms of any slip rental or boat loan before assuming coverage is optional. That is a different starting point from a car, where registration itself sets a minimum.

Does my policy cover the trailer?

Usually as a listed item, and sometimes automatically at a low limit. Worth confirming rather than assuming, since losses can happen on the road.

What about a personal watercraft?

Different form, usually its own policy, and priced on its own terms. Ask when you call.

Am I covered if someone else drives my boat?

Typically yes, within the policy's operator terms, but permissive use language varies. If other people regularly run the boat, say so.

Does it cover hurricane damage?

Named-storm terms vary and often include specific haul-out or preparation requirements. This is the clause to read in Florida before any other.

Can you add this to my home and auto?

Yes. Multi-policy arrangements are common through an independent agency that places home, car and boat together, and reviewing all three together usually surfaces sublimits nobody had noticed. Home quotes for the same household come from the same call, and an umbrella can often sit above the boat's liability when the boat policy is listed as underlying.

Not sure yet?

Walk through your policy with a licensed Florida agent by phone, at no charge.

(352) 662-9995Or send the short form

Compare well ahead of your renewal date

Share your details one time. A licensed Florida agent shops them for Ocala, Marion County and the surrounding communities, and you make the call.