Commercial Insurance in Ocala, FL

Commercial insurance in Ocala: a personal auto policy isn't written to pay a business-use claim, so work trucks and vans need commercial auto.

On InsuranceOcalaFL.com, Matt Williams, a licensed Florida agent, passes business requests to a licensed agent on his team.

  • Licensed Florida agent since 2010
  • 17 deaths in Marion commercial vehicle crashes (FLHSMV 2024)
  • 324 hurt in Marion commercial vehicle crashes (FLHSMV 2024)
  • Ocala's mean commute to work: 19.2 minutes (Census)
  • Marion Oaks: 33.5-minute mean commute (Census)

Employees running jobs in their own cars? See what a car insured only to the state minimum leaves unpaid.

See how far a liability limit stretches

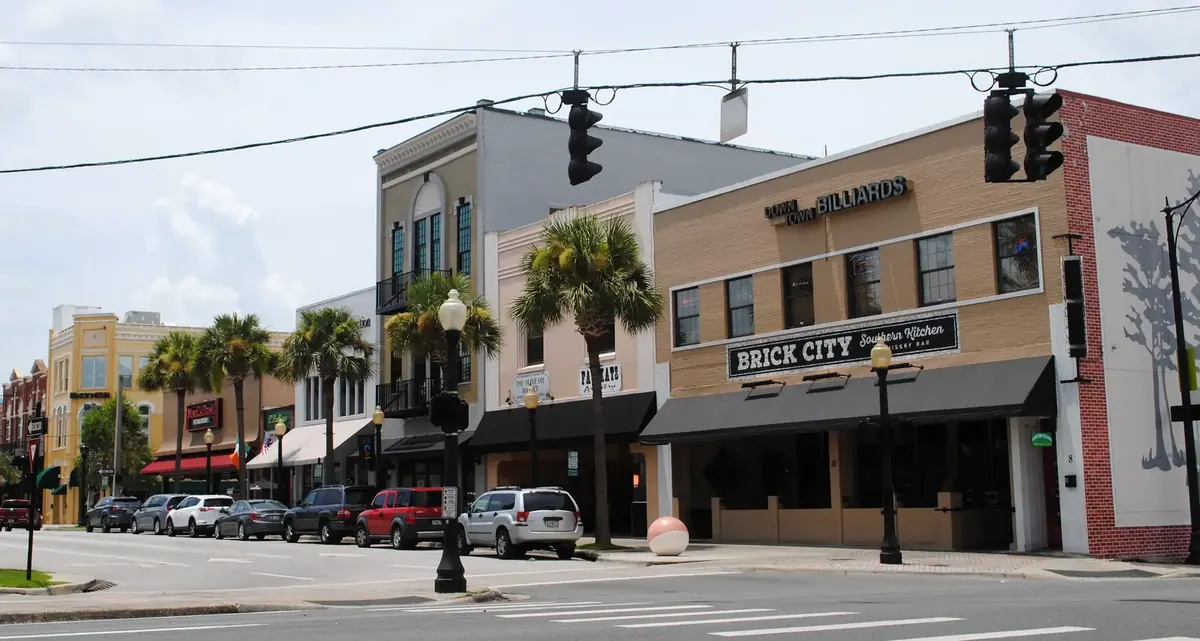
Historic downtown Ocala, Florida
Historic downtown Ocala

No repeating yourself to agency after agency, and asking changes nothing on your current policy.

Work vehicles are where a personal policy most often leaves a business exposed, so this page starts there, then covers the commercial lines beyond basic liability.

For the basic liability and property package, start with what a small business needs before a certificate request arrives.

Work Vehicles Are the Gap Worth Closing First

A personal auto policy is not written to pay a business-use claim. A truck with a company name on the door, a van carrying tools between job sites, or a car making deliveries is being used commercially, and a personal policy can decline on exactly that basis.

What a Commercial Auto Policy Handles

  • Liability at limits contracts usually require, rather than personal-policy limits
  • Physical damage on vehicles with upfits, racks, liftgates and specialty bodies
  • Hired and non-owned auto, for employees driving their own cars on company business
  • Trailers, which are routinely left off policies entirely
  • Tools and equipment in transit, which the auto policy itself does not cover

Marion County roads by the numbers

  • 6,532crashes reported in Marion County in 2024
  • 114people killed in Marion County crashes in 2024
  • 4,959people injured in Marion County crashes in 2024
  • 195motorcycle crashes in Marion County in 2024

Source: FLHSMV Traffic Crash Facts, 2024 annual report; figures checked

The Rest of the Commercial Lines Belong in the Same Comparison

Commercial Property

The building if you own it, tenant improvements if you lease, plus contents, stock and equipment. Business interruption coverage sits alongside it and pays the income lost while the premises are unusable, which is frequently worth more than the contents themselves. If the building sits near a river or a lake, check the flood zone on its parcel before the property quote.

Inland Marine

Tools, equipment and materials that move. For contractors and equipment-based operations this is a core line, not a niche one.

Excess and Umbrella Liability

A layer above the general liability limits and their aggregate and the commercial auto limits. Contracts increasingly demand limits above what a base policy carries, and an excess layer is usually the cheaper route to meeting them. It is not the same product as a personal umbrella, which excludes business activity.

Workers' Compensation

Requirements depend on your industry and how many people you employ, so confirm where your business falls before assuming it is exempt.

The Trades Price Differently, So One Quote Is Not Enough

Classification drives commercial pricing more than anything else, and construction trades, landscaping, agriculture and equipment-based operations are among the classes that cost more to insure.

Two things follow. Getting the classification right matters, because an approximate code can cost thousands over a policy period or leave a claim disputed. And appetite varies sharply between carriers by class, so a trade that one carrier prices punitively may be another's target business. That is the single strongest argument for shopping a commercial policy rather than renewing it unexamined, and shopping it through an independent agency puts many companies' answers side by side.

Certificates, Additional Insureds and Contracts: Check Before You Sign

Most commercial insurance friction is contractual. A general contractor requires certain limits, an additional insured endorsement, sometimes a waiver of subrogation, and occasionally primary and non-contributory wording.

Each of those is a specific thing with a specific cost. Sign the contract first and you may be committed to coverage that is expensive or unavailable. Read the insurance clause before signing and the conversation gets much cheaper.

Commercial Insurance Questions

My truck is in my personal name. Is that a problem?

Possibly. What matters is how the vehicle is used, not whose name is on the title. If it is used for business, the policy should reflect that.

Do I need commercial auto for one van?

If the van is used for business, yes. Fleet size is not the test; use is.

What about employees driving their own cars?

That is hired and non-owned auto coverage. It is inexpensive and it is one of the most commonly missing endorsements.

How much liability do I need?

Usually whatever your contracts require, and often a step above it. The requirement is the floor, not the recommendation.

Can you cover tools stored in the truck overnight?

That is an inland marine question, and theft from vehicles is a specific thing to confirm rather than assume.

Can you review my current commercial policy?

Yes, and the classification is the first thing worth checking. Send the declarations page.

Not sure yet?

Walk through your policy with a licensed Florida agent by phone, at no charge.

(352) 662-9995Or send the short form

Compare well ahead of your renewal date

Share your details one time. A licensed Florida agent shops them for Ocala, Marion County and the surrounding communities, and you make the call.