Florida rules, explained for Marion County

4-Point and Wind Mitigation Inspections for Marion County Homes

4-point inspections in Marion County: the report covers roof, plumbing, electrical and AC, and each company reads it against its own guidelines.

On InsuranceOcalaFL.com, Matt Williams, a licensed Florida agent, compares 80+ companies for you.

  • $0 to compare; the company pays the agent
  • 29.7% of Marion County residents are 65 or older (Census)
  • Median Ocala home value: $241,400 (Census)
  • Home rate filings must include wind credits (s. 627.0629)
  • Hip roofs and storm shutters can earn discounts (Citizens)

Once the report is clean, have the Ocala house priced by the companies whose rules it passes.

Put your hurricane deductible in dollars

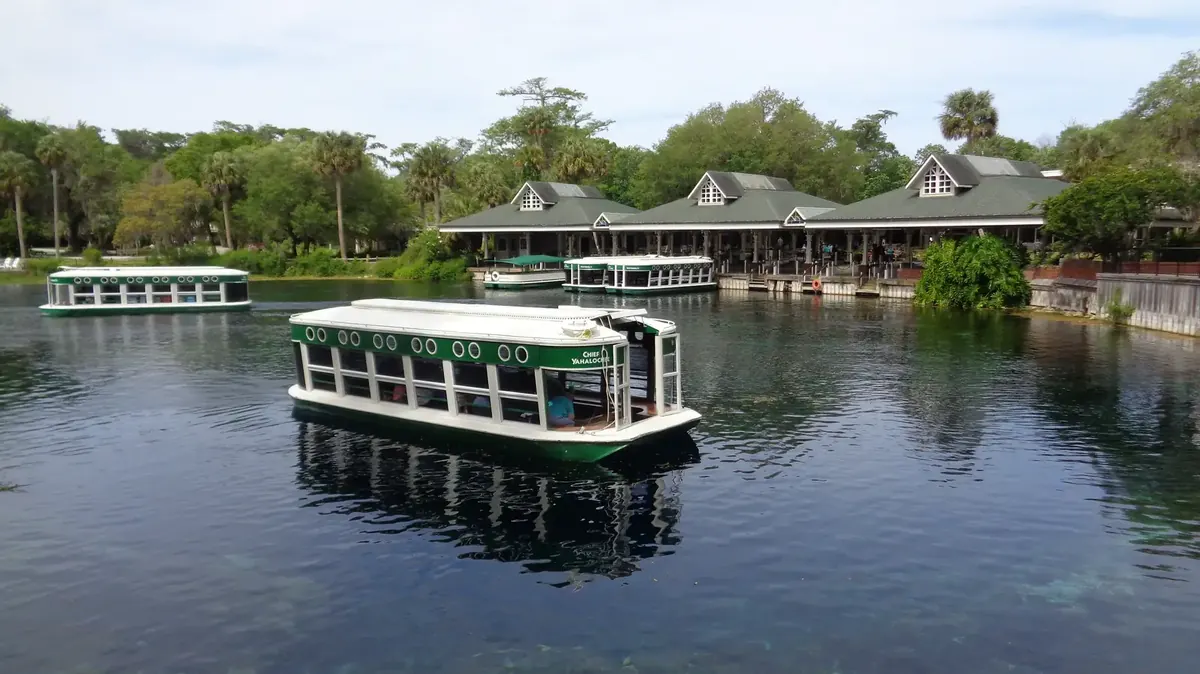
Glass-bottom boats at Silver Springs State Park near Ocala, Florida
Glass-bottom boats, Silver Springs State Park

Because every carrier writes its own guidelines, a report that passes with one can fail with the next. Learn that before the inspector is booked and you gain time for repairs.

Call (352) 662-9995 for same day quotes. Asking for quotes does not touch the policy you have now.

A Report Passes or Fails Against One Carrier's Rules

There is no general pass mark for a 4-point inspection. A report passes or fails only against a particular carrier's guidelines, and carriers do not work from a shared set. A double-tapped breaker is grounds to decline for one carrier and a noted item for another.

Why does that matter? Looser guidelines and a lower price sometimes come from the same carrier. Placing your Ocala home with that carrier first can give you a year to make updates when it suits you, rather than rushing them before coverage can bind. Agents do not all reach the same carriers. The agent here has access to many, so your inspection result can go to the carrier that will take it.

Four Systems, Photographed and Dated

The inspection looks at four systems: roof, plumbing, electrical and HVAC. Each one gets photographed, and the inspector records how old it is and what shape it is in, noting anything that could lead a carrier to decline the home or ask for repairs.

It is narrower than a full home inspection: a quick record of the four systems most likely to produce a claim. It does not look at the foundation, so cracks there are a question for the sinkhole coverage on the policy.

The Checklist, One System at a Time

Every age below is a range observed across the admitted market in October 2026, not any one carrier's position. Each carrier owns its underwriting guidelines, keeps them private and revises them.

Point One: Roof

  • Every tile whole and seated, every shingle present and lying flat.
  • Nothing patched, tarped or left damaged and unrepaired.
  • A clear answer on age and useful life left, which is also the test the roof age law turns on. Many carriers want the remaining years stated as a number, and some ask for proof of when the roof was replaced, such as a permit or a receipt.
  • Flashing, gutters and boots intact and sealed.

Point Two: Plumbing

  • Dry everywhere: no leak, current or recent, at the main, at the water heater or under a sink.
  • Shut-off valves that work at each fixture and at the main. Give every one a turn before inspection day so you know it moves.
  • Clean pipe stub-outs. Old staining looks like a live leak in a photo, so scrub them with a CLR-type cleaner and the picture will show clean pipe.
  • The water heater's age, printed as the manufacture date on its label. Expected life is often 12 to 15 years, and some carriers flag a unit past that point even when it still works. Make sure a temperature and pressure relief valve is in place and piped.
  • What the pipes are made of. Supply lines of polybutylene or galvanized pipe, and cast-iron drains, get extra scrutiny by themselves.

Point Three: Electrical

  • No bare wiring in sight, and that includes any junction box without a cover.
  • Inside the panel, no breaker with two wires under it (a double tap).
  • The panel's brand. Many carriers decline Federal Pacific, Zinsco and some Challenger panels no matter what condition they are in.
  • Aluminum branch wiring, common in homes built from 1965 to 1973. Expect a flag, though some carriers accept it once remediation is documented.
  • GFCI protection on kitchen, bathroom and outdoor outlets.

Point Four: AC and HVAC

  • A system that runs and cools during the visit, so turn it on ahead of time.
  • A condensate drain line that is clear and draining. A clogged line shows up among the most common flags, and it ranks among the least expensive to fix.
  • The age of the condenser and air handler. Past 15 to 20 years, units draw questions even while they still work.
  • No rust-through you can see, no ducts pulled loose and no covers missing.

Getting Ready for Inspection Day

  1. Take this list through the house and clear the inexpensive items first: the drain line, stiff valves, stained stub-outs, and breaker or outlet covers.
  2. Pull your records together: the roof's permit or invoice, the water heater receipt, permits for any electrical or plumbing work, earlier inspection reports, and an elevation certificate if the house has one.
  3. Photograph the electrical panel with its cover removed, then the water heater's label, then the roof from ground level. An agent can check those pictures against carrier guidelines before the inspection costs you anything.
  4. Expecting a major item to fail, such as an FPE panel or a roof with no life left? Bring it up with your agent ahead of the inspection, not once the report is in. That talk settles which carrier gets tried first.

Where the Wind Mitigation Report Fits

The two inspections answer different questions, and one visit often covers both. A carrier reads the 4-point to decide whether it will write the home at all. The wind mitigation report shapes what you pay. It records opening protection, roof shape, roof deck attachment, roof-to-wall connections and secondary water resistance, the features Citizens lists for its wind discounts, and s. 627.0629, Florida Statutes requires insurers' rate filings to include credits for features that reduce windstorm loss. When you book one, ask whether the same inspector can do the other. Both reports also go with the private quotes you line up after a Citizens takeout letter.

Find Out Which Carriers Fit Before You Pay

Send photos of the panel and the water heater, plus the home's age and the roof's year. You will learn which carriers are realistic before any money goes to an inspector.

Sources

Compare well ahead of your renewal date

Share your details one time. A licensed Florida agent shops them for Ocala, Marion County and the surrounding communities, and you make the call.