For agents and lenders closing in Marion County

Home Insurance for Closings in Ocala, FL

Realtors and loan officers in Marion County: introduce the buyer early, and a licensed agent prices the lender's required coverage with many companies before closing day.

The short version

Home insurance for Ocala closings goes smoothly when four items get settled early in escrow: the roof's age, the inspection reports, the buyer's sinkhole coverage choice and the parcel's flood zone. Refer the buyer on this page and attach the seller's paperwork. A licensed agent then compares many companies on that home before the closing date.

  • Insurers must allow an inspection before requiring an older roof's replacement
  • A flood policy usually starts only after a waiting period
  • Every referred buyer is phoned by hand, never by an autodialer

Call (352) 662-9995 to talk it over with a licensed Florida agent.

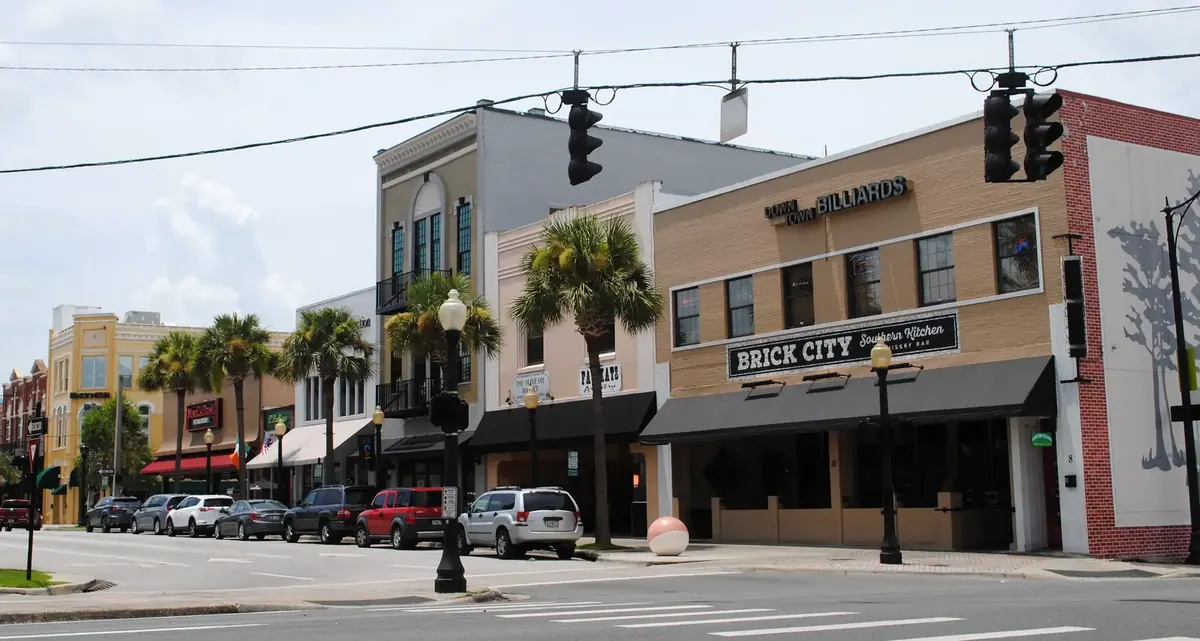
Historic downtown Ocala, Florida
Historic downtown Ocala

Realtors and loan officers, the rule is simple: have the buyer's home insurance quoted early. The closing date then holds, and nobody spends the final week chasing a policy.

The four issues that stall Marion County home closings are covered below. After them come a short referral form and a one-page closing checklist to print and keep with the file.

Start the Home Insurance Early in Escrow

Every Marion County resale raises the same insurance questions. How old is the roof? What do the inspection reports say? Which sinkhole coverage does the buyer want? Does the parcel sit in a mapped flood zone? Answering any one of them takes days, not hours.

Once the Home Is Under Contract

Share the buyer's details, plus anything the seller can pass along: the current declarations page, the roof's age and any recent inspection reports. A quote that starts from real facts will not need a second pass.

While the Home Is Being Inspected

If a carrier is likely to ask for the 4-point and wind mitigation reports, book them together with the home inspection. Often a single visit covers both.

In the Days Before Closing

Three steps close it out. The buyer says yes to a policy, the policy names the lender as mortgagee, and the lender receives proof of insurance whose effective date lines up with the closing.

Roof Age: Settle It Before It Stalls the Closing

On an older Ocala home, a carrier usually asks about the roof's age before anything else. Before the buyer starts shopping, know the two lines that s. 627.7011, Fla. Stat. draws.

Roofs Younger Than 15 Years

If the roof is less than 15 years old, the insurer may not point to its age as the sole reason for refusing to issue or renew a homeowner's policy.

Roofs 15 Years or Older

For a roof this old, the homeowner can pay an authorized inspector to examine it. The insurer has to allow that inspection before it makes replacement a condition of issuing or renewing the policy. Should the inspector find five or more years of useful life left, the insurer may not refuse to issue or renew on roof age alone. Order that roof report early, since it is often the paper that keeps the closing date in place. Details are in the roof age rules guide.

Inspection Reports: Book Them Alongside the Home Inspection

For underwriting, a carrier may want a 4-point inspection, a report on four systems: roofing, electrical, plumbing and HVAC. Each carrier decides for itself whether it needs one. When an item fails, the fix is often a repair, a receipt and a re-inspection.

The wind mitigation inspection documents features like opening protection, roof-to-wall strength and how the roof covering performs. Under s. 627.0629, Fla. Stat., rate filings for residential property have to include credits for those features, which is why the report can affect the buyer's premium. More on both reports: 4-point and wind mitigation inspections.

Sinkhole Coverage: Make Clear Which Kind the Buyer Has

Florida requires every authorized property insurer to provide catastrophic ground cover collapse coverage. That coverage is narrow. For it to apply, all four must be true: the collapse is abrupt, the depression is visible to the naked eye, the building is structurally damaged, and the structure is condemned and ordered vacated.

Sinkhole loss coverage reaches further, and it is optional. Insurers have to offer it for an additional premium under s. 627.706, Fla. Stat., with a choice of deductibles at 1, 2, 5 or 10 percent of the dwelling limit. Buyers relocating to Marion County often assume they already have it. The quote should state plainly which of the two the policy carries, and the sinkhole guide explains how they differ.

Flood: Confirm the Zone Before the Buyer Commits

In FEMA terms, a zone beginning with A or V is a high-risk Special Flood Hazard Area, and areas of moderate or minimal hazard still count as mapped flood hazard areas. A standard homeowners policy leaves flood out, which is why flood cover for the parcel is priced as its own policy.

The timing is what trips up closings. FEMA states that a 30-day waiting period from the date of purchase typically applies before a flood policy goes into effect, and that exceptions exist. So raise flood when the contract is signed, not once the file reaches clear to close. For the local zones, see the Marion County flood zones guide.

Refer the Buyer and Attach the Seller's Papers

One short form moves the insurance side of the deal off your desk. If you have the home's inspection reports or the seller's current declarations page, attach them.

The call to the buyer comes from Matt Williams or a licensed agent from his team, who confirms the home's details and compares many companies on the same coverage. The buyer makes the decision.

Since the buyer gave no consent for automated calls or texts, contact with the buyer is limited to a personal phone call. As for your own details, they are used to update you on how the referral is going.

This consent applies to you, the referring professional. The buyer has not consented, so the agent contacts the buyer by hand only: a personal call, never a text or an automated dialer. Sending a referral leaves every policy as it is: nothing is bound, cancelled or changed.

The checklist fits on one page for the file. It lists the home insurance steps Marion County closings usually call for, in the sequence they arise. Print it, save the PDF, check items off as you go, or give it to the buyer. Its QR code links straight to the referral form, so a buyer can ask for a quote in one scan.

Realtor and Lender Questions, Answered

How early should the buyer begin shopping for home insurance?

Right when the contract is signed. A home quote on an Ocala house depends on the roof's age, the inspection reports and the flood zone, and gathering some of that takes days. An early start leaves time to fix any problem a carrier or the lender brings up.

What will the lender want to see?

In most cases, the lender looks for three things on the proof of insurance: the lender named as mortgagee, limits that meet its conditions, and an effective date no later than closing. Since each lender writes its own conditions, include that written list when you refer the buyer.

Does a roof older than 15 years sink the deal?

Not necessarily. Before an insurer can require a new roof, it has to allow an inspection. When that inspection finds five or more years of useful life remaining, the insurer cannot refuse to issue or renew because of roof age alone. Get the inspection ordered early, and see the year a roof crosses the fifteen-year line on the homepage calculator.

Will the buyer have to carry flood insurance?

That turns on two things: the parcel and the lender's written conditions. Start by checking the flood zone. Since a flood policy typically comes with a 30-day waiting period, make the call well ahead of closing.

Does the buyer get texts or automated calls?

No. You filled in the form, not the buyer, so the buyer gets only a personal phone call: no texts and no automated calls.

Is a quote enough to cover the buyer at closing?

No. A quote only shows what a company is prepared to offer, and it binds nothing. Coverage begins only after the buyer accepts the policy and the company issues it with the correct effective date.

Not sure yet?

Walk through your policy with a licensed Florida agent by phone, at no charge.

(352) 662-9995Or send the short form

Compare well ahead of your renewal date

Share your details one time. A licensed Florida agent shops them for Ocala, Marion County and the surrounding communities, and you make the call.